After a house fire, most Arizona homeowners are dealing with two crises at once: the emotional weight of what happened and a fast-moving insurance claim they've never navigated before. Insurance carriers move quickly — often adjusters are on-site within 24 hours — and the decisions you make in the first three days shape the entire rebuild. This guide walks through what a licensed fire damage restoration contractor handles, what your policy actually covers in Arizona, and where claims get denied.
The First 72 Hours
- Wait for the fire marshal to clear the structure before re-entering — even small fires produce toxic residues
- Contact your insurance carrier and open the claim the same day
- Photograph and video everything before anything is moved or cleaned
- Secure the property (board-up, tarp, temporary fencing) — this is a policy-required mitigation step
- Start a running inventory of damaged contents with rough replacement costs
Most Arizona carriers require "reasonable steps to prevent further damage" as a condition of coverage. Skipping the board-up and tarp step can lead to a partial denial if secondary water or wind damage follows.
What Arizona Homeowners Policies Typically Cover
- Dwelling (Coverage A): Structural rebuild — framing, roof, drywall, systems
- Other Structures (Coverage B): Detached garage, casita, block wall
- Personal Property (Coverage C): Contents at replacement cost if you have RCV coverage, actual cash value otherwise
- Loss of Use (Coverage D): Hotel, rental, and additional living expenses while displaced
- Debris removal, code upgrades, and ordinance coverage: Often sub-limited — read your policy
The Coverage Gaps That Bite Arizona Homeowners
- Underinsurance: Rebuild costs in Phoenix rose 30%+ from 2021–2026. Policies written before 2023 often carry dwelling limits that no longer cover a full rebuild.
- Code upgrade coverage: Older Phoenix and Mesa homes often need electrical, HVAC, or structural upgrades to meet current code. Without a code endorsement, you pay the difference.
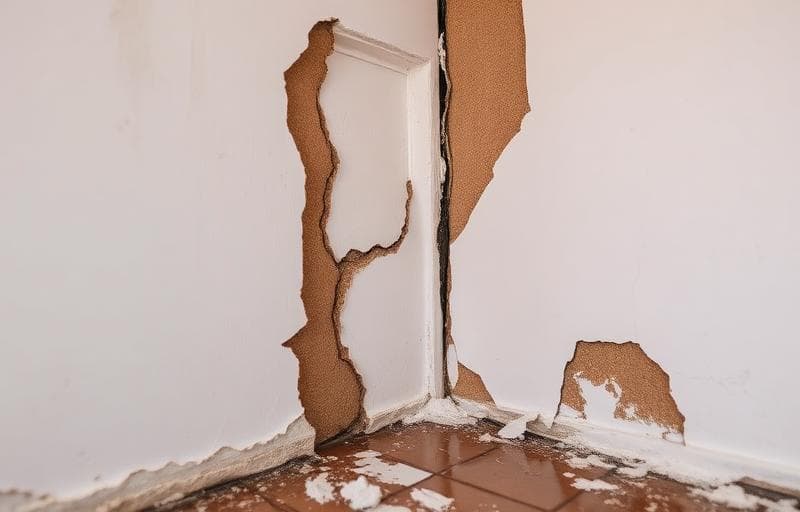
- Smoke damage in adjacent rooms: Adjusters often scope only the visibly burned areas. Smoke residue migrates through HVAC systems into rooms far from the fire and requires professional smoke damage restoration.
- Contents depreciation: ACV policies pay depreciated value up front and reimburse the balance only after you replace and submit receipts.
Working With the Adjuster
The insurance adjuster works for the carrier, not for you. That doesn't make them the enemy — most are fair — but their scope of loss is a starting point, not a final number. A licensed restoration contractor writes an independent scope in the same estimating software (Xactimate) and negotiates line items directly. This is standard practice in Arizona and it's how most homeowners recover 15–40% more than the initial offer.
Timeline: What to Expect
- Day 1–3: Board-up, secure, initial adjuster visit, contents pack-out
- Week 1–2: Structural drying, soot and smoke cleaning, air quality testing
- Week 2–6: Demo, scope negotiation, permits (City of Phoenix or Mesa)
- Month 2–6: Rebuild — framing, systems, drywall, finishes
- Total: 3–9 months for typical residential fire claims in Arizona
Common Reasons Arizona Fire Claims Get Denied or Reduced
- Late notification (most policies require prompt reporting)
- Skipped mitigation steps (no board-up, no tarp)
- Undocumented contents (no pre-loss inventory or receipts)
- Wear-and-tear or maintenance exclusions cited on aging systems
- Unpermitted prior work discovered during rebuild scoping
What ProWorx Handles
As a licensed general contractor and insurance restoration specialist, ProWorx runs the whole process: 24/7 emergency response, board-up, soot and smoke mitigation, contents inventory, Xactimate scope writing, adjuster negotiation, permitting, and full rebuild. One point of contact, one project manager, one signature.
Just Had a Fire?
Call for an emergency response, or book a same-day inspection. We serve homeowners across Phoenix, Mesa, Scottsdale, and the wider Valley — with the licensing, insurance experience, and rebuild capacity to take a home from ashes back to move-in ready.
What Your Policy Pays: Replacement Cost or Actual Cash Value
This single distinction affects a fire claim more than almost anything else. A replacement cost policy pays what it costs to replace damaged property with new property of like kind and quality today. An actual cash value policy pays replacement cost minus depreciation, so a ten-year-old roof is settled as a ten-year-old roof.
Many replacement cost policies pay in two stages. They first release the actual cash value, then release the withheld depreciation once repairs are actually completed and documented. That means money arrives in instalments, and the final portion depends on finishing the work and submitting proof. Knowing which structure your policy uses before you start spending prevents an unpleasant gap partway through the rebuild.
Additional Living Expenses
If a fire makes your home uninhabitable, most homeowner policies include coverage for additional living expenses, often abbreviated ALE. This is intended to cover the difference between your normal cost of living and what you spend while displaced: temporary accommodation, meals above what you would ordinarily spend, laundry, pet boarding and extra mileage.
ALE is usually capped, either as a percentage of the dwelling coverage or by a time limit, and it requires documentation. Keep every receipt from the first night onward. Families who treat ALE casually at the start often find themselves unable to substantiate months of expenses later.
Documenting Contents Room by Room
Contents claims are where most of the paperwork lives, and where the most value is left unclaimed. Insurers typically want a description of each item, its approximate age, the original or replacement cost, and ideally a receipt or photograph. Working room by room, including closets, the garage and storage areas, is far more reliable than trying to list from memory.
Do not discard damaged belongings until they have been photographed and recorded, even if they are obviously ruined. If items have been removed for cleaning or storage, keep the inventory the restoration company provides. Smoke-affected clothing, electronics and furniture may be restorable, and separating what can be cleaned from what must be replaced affects both the claim and the cost.
Code Upgrade Coverage
When a home is substantially damaged, rebuilding often has to meet current building codes rather than the codes in force when the house was built. That can mean upgraded electrical, additional insulation, different structural connections or new egress requirements, none of which existed in the original structure.
Standard policies do not always cover the additional cost of those upgrades. Some include ordinance or law coverage as an endorsement, sometimes with its own limit. If your rebuild triggers code requirements, identify early whether your policy covers them, because the difference can be substantial on an older Arizona home.
When the First Estimate Is Short
It is common for an initial insurance scope to miss items, particularly hidden damage that only appears once demolition starts. Smoke that travelled into wall cavities, water damage from firefighting beneath flooring, and framing weakened by heat are all routinely discovered after the first inspection.
These are handled through supplements: additional documented items submitted for review. Photographs, measurements, moisture readings and contractor estimates support them. A contractor who documents thoroughly as the work proceeds makes supplements straightforward rather than contentious, which is why documentation habits matter as much as construction skill on an insurance rebuild.
You Choose Your Own Contractor
Insurers often maintain preferred contractor programmes and may recommend one strongly. In Arizona, the choice of who repairs your home is yours. A preferred contractor may be perfectly good, but the relationship runs through the insurer, and some homeowners prefer a contractor whose only obligation is to them.
Whichever you choose, verify the Arizona ROC licence is active and covers the work, confirm liability and workers' compensation insurance, and insist on a written, itemised scope. Be cautious of anyone asking you to sign a broad authorisation or assignment of benefits before you have read it carefully.
Keeping Records From Day One
Keep a single file, physical or digital, containing every piece of correspondence, each estimate, all photographs, receipts and a dated log of phone conversations including who you spoke to and what was agreed. Claims that run for months are far easier to manage, and far easier to dispute if necessary, when that record exists from the beginning rather than being assembled from memory at the end.