Arizona's monsoon season pounds roofs with 60+ mph winds, hail, and torrential rain. When water starts dripping through your ceiling, the next call is usually to your insurance company. Here's what most Arizona homeowners policies actually cover — and the steps to file a claim that gets paid.
What's Usually Covered
- Wind-damaged shingles or tiles from a named monsoon storm
- Hail damage to roofing materials
- A tree falling on your roof
- Interior water damage caused by the sudden roof failure (drywall, flooring, contents)
- Mold remediation if it stems from a covered loss (usually capped at $5K–$10K)
What's Usually NOT Covered
- Wear and tear from a roof at end of life (20+ years)
- Slow leaks that went unreported for months
- Poor maintenance or improper prior repairs
- Damage from pests, rodents, or birds
- Cosmetic damage on some HO-3 policies (look for "cosmetic exclusion")
5 Steps to a Successful Claim
- Document everything immediately. Photo and video the roof, ceiling stains, soaked carpet, and damaged contents before cleanup.
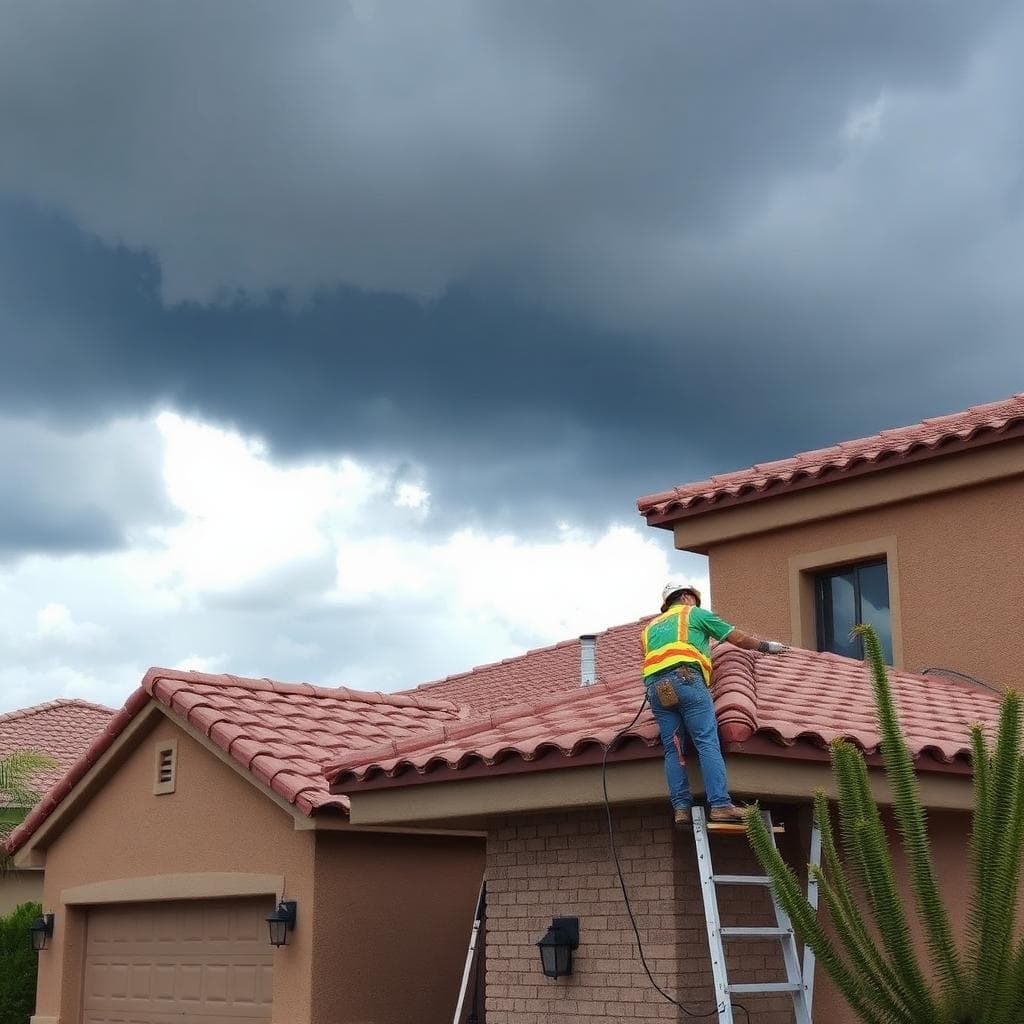
- Mitigate further damage. Tarp the roof, move belongings, and start water extraction. Your policy requires reasonable mitigation — keep receipts.
- File within the policy window. Most Arizona policies require notice within 60 days; sooner is better.
- Get an independent estimate. Don't let the insurer's preferred vendor be the only voice. A licensed restoration contractor can supply a competing estimate.
- Push back on lowball offers. First offers often miss 20–40% of actual scope. Ask for a re-inspection if your contractor's estimate is materially higher.
Why Arizona Claims Get Denied
The #1 reason: the adjuster classifies damage as "long-term deterioration" instead of a sudden event. Beat this with dated photos showing the roof was intact before the storm, and a contractor's letter tying damage to a specific weather event (NOAA weather data helps).
How ProWorx Helps
We handle water damage restoration end-to-end and work directly with adjusters from every major Arizona carrier. We document scope thoroughly, supply competing estimates when needed, and rebuild your home back to better-than-before. Contact us after any monsoon damage — the first inspection is free.
Sudden and Accidental Versus Gradual
This single distinction decides most Arizona roof leak claims. Policies generally cover damage that is sudden and accidental, such as a monsoon storm lifting tiles and driving rain into the house. They generally exclude damage resulting from wear, age, deterioration or lack of maintenance.
A roof that failed because wind damaged it during an identifiable storm is a different claim from a roof that has been leaking slowly for two years because the underlayment reached the end of its life. The second is usually treated as a maintenance issue rather than an insured loss.
Roof Age Changes the Settlement
Many policies treat older roofs differently, settling them at actual cash value rather than replacement cost. Actual cash value deducts depreciation, so a roof with most of its expected life behind it may be settled for considerably less than a replacement costs.
Some policies apply this through a roof schedule or a specific endorsement, and the details vary. Knowing which applies to yours before a storm, rather than discovering it during a claim, is one of the more valuable things an Arizona homeowner can check.
The Leak and the Damage Are Separate
Homeowners are frequently surprised that a policy may pay to repair the water damage inside the house while declining to pay for the roof itself. That is a common outcome when the roof failed through age but the resulting interior damage was sudden.
It is not inconsistent. The policy covers the sudden consequence, not the deteriorated component that caused it. Understanding that in advance prevents the sense that a claim was unfairly handled.
Why Arizona Roofs Fail Where They Do
On tile roofs, the tile is a rain shield and the underlayment beneath is the actual waterproof layer. That underlayment degrades under sustained heat and ultraviolet exposure long before the tile looks aged, which is why a roof can appear sound from the ground and leak persistently.
On flat and low-slope roofs, failures concentrate at seams, parapet flashing, and penetrations around rooftop air-conditioning units and vents. Ponding water accelerates all of them.
Documenting a Storm Claim
If a storm damaged your roof, documentation made in the first hours carries the most weight. Photograph displaced tiles, debris, damaged flashing, interior staining, wet insulation and affected belongings before anything is cleaned or moved. Note the date and time of the storm.
Report the claim promptly and arrange temporary protection such as tarping. Keep receipts, because most policies expect you to take reasonable steps to prevent further damage and will generally treat those costs as part of the claim.
Maintenance Records Help Your Claim
Because the dividing line is often sudden damage versus deterioration, evidence that the roof was maintained strengthens a claim considerably. Records of inspections, repairs, cleaning and any previous work establish that the roof was being looked after.
Photographs of the roof in good condition before storm season are similarly useful. It costs nothing to take them each spring and they can make a material difference to how a claim is assessed.
When the Adjuster Says No
A denial or a partial payment is not necessarily the end. Ask for the decision in writing with the specific policy language relied upon. Detailed documentation, a roofing contractor assessment and photographs can support a request for reconsideration.
Many policies also contain an appraisal clause, which provides a defined process for resolving disagreements about the amount of a loss. Public adjusters, who represent policyholders for a percentage, are an option on larger claims; confirm licensing and fees before signing anything.
Deductibles and Whether to Claim
Not every leak is worth claiming. If the repair cost is close to or below your deductible, filing achieves nothing and puts a claim on your record that may affect future premiums or renewability.
Some Arizona policies also carry a separate, percentage-based wind or hail deductible that is considerably higher than the standard one. Checking which deductible applies before filing is worth doing, because it changes the arithmetic significantly.
What to Do Before the Next Storm
Read the roof section of your policy now rather than during a claim. Confirm your deductible, whether the roof is settled at replacement cost or actual cash value, and whether any roof-specific endorsement applies.
Then inspect and maintain: clear valleys and drains, repair cracked tiles and failed flashing, reseal around penetrations, and photograph the result. Maintenance both reduces the chance of a leak and strengthens any claim you do need to make.
Interior Damage and Contents
When a covered roof leak damages the inside of the house, the claim usually extends well beyond the ceiling. Wet insulation loses its value and generally has to be removed and replaced. Drywall that has absorbed water is cut out rather than dried in place. Flooring, cabinetry and painted surfaces may all be affected, and personal belongings damaged by water are typically covered under the contents portion of the policy, which carries its own limits and may settle differently from the structure.
Document contents as carefully as structure. Photograph affected belongings before moving them, keep a room-by-room list with approximate ages and values, and do not discard anything until it has been recorded, however obviously ruined it appears.
Mould After a Roof Leak
Many Arizona policies limit or exclude mould coverage, which matters because a roof leak that went undetected through a monsoon season has had ideal conditions to produce it. Where mould results from a covered sudden loss and mitigation began promptly, it is often treated differently from mould arising through a long-term leak or neglect.
That distinction is another reason speed matters. Documentation showing when the leak was discovered and how quickly drying started is frequently what separates a covered remediation from a declined one.